Market overview and structural scope of the Surface Electronic Warfare Improvement Program (SEWIP) Block 4 Roadmap Market
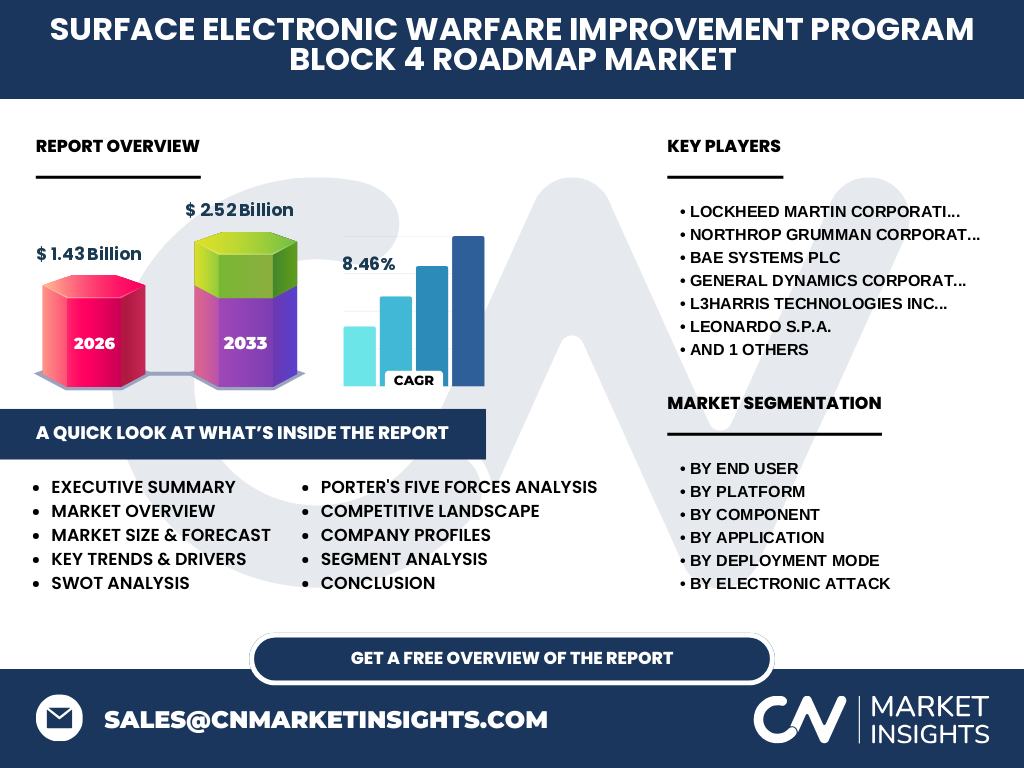
Our analysis indicates that the Surface Electronic Warfare Improvement Program (SEWIP) Block 4 Roadmap Market represents a vital naval modernization frontier. Valued at 1.43 Billion in 2026, the sector encompasses advanced electronic attack and electro-optical/infrared countermeasures. Industry significance stems from its role in countering evolving anti-ship missile threats through sophisticated photonic and radio frequency integration across global defense fleets.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating maritime geopolitical tensions and increased defense budget allocations toward electronic warfare. Key restraints include stringent ITAR compliance, prolonged Department of Defense acquisition cycles, and complex supply chain vulnerabilities regarding Gallium Nitride raw materials. Technological complexity in integrating high-powered laser capabilities into legacy ship hulls further challenges rapid deployment schedules.
Emerging Trends and Technological Shifts in the Surface Electronic Warfare Improvement Program (SEWIP) Block 4 Roadmap Market
The sector is witnessing a definitive pivot toward cognitive electronic warfare and artificial intelligence-driven signal processing. Machine learning algorithms are being embedded into threat identification systems to autonomously classify novel radar frequencies at sea. This transition heavily favors agile innovators capable of software-defined upgrades over hardware-locked legacy architectures.
Evaluating the COVID-19 Impact and Post-Pandemic Recovery Trajectory
Pandemic-induced shipyard labor shortages and microchip scarcity temporarily disrupted component procurement for naval electronics. However, post-pandemic recovery has accelerated due to bipartisan legislative focus on maritime defense resilience. Our research shows that supply chain diversification strategies have successfully restored baseline manufacturing velocity across major defense contractor hubs.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, dominated by prime defense contractors possessing deep systems-integration expertise. Firms like Lockheed Martin Corporation and Northrop Grumman Corporation leverage expansive R&D budgets to secure prime contracts, while specialized suppliers focus on niche signal detection and cyber protection sub-systems.
Executive Summary: High-Level Synthesis of the Surface Electronic Warfare Improvement Program (SEWIP) Block 4 Roadmap Market
The Surface Electronic Warfare Improvement Program (SEWIP) Block 4 Roadmap Market stands at an inflection point of technological modernization. Driven by urgent fleet protection mandates, the sector exhibits robust fundamentals. Strategic stakeholders must align their capital allocation with cognitive EW and directed energy capabilities to capture upcoming procurement waves.
Market Forecast and Long-Term Projections (2027 to 2033)
Based on our econometric modeling, the market is projected to expand from 2.52 Billion by 2033, surging at a compound annual growth rate of 8.46% from 2027. This accelerated expansion is underpinned by scheduled fleet-wide retrofits and the integration of advanced electronic countermeasure payloads across allied naval forces.
Segmentation Analysis Across End Users, Platforms, and Components
Segmentation is analyzed across End User (Defense, Homeland Security, Naval Forces), Platform (Destroyers, Aircraft Carriers, Amphibious Ships, Littoral Combat Ships), and Component (Electronic Support, Electronic Attack, Electronic Protect). Naval forces operating destroyers represent the primary revenue-generating node due to their front-line deployment profiles requiring maximum electromagnetic survivability.
Geographic Distribution and Regional Market Performance
Regional performance is heavily anchored by North America, driven by extensive United States Navy procurement initiatives. The Indo-Pacific region follows as the fastest-growing market, fueled by regional naval buildups and territorial defense imperatives. European maritime nations represent a steady secondary tier focusing on interoperability and NATO standardization.
In-Depth Regional Review of Deployment Constraints and Opportunities
Regional analysis highlights contrasting procurement priorities. North American markets emphasize cutting-edge technological superiority and rapid prototyping. Conversely, the Indo-Pacific theater prioritizes rapid scalability and electronic robustness against congested littoral electromagnetic interference, directly shaping regional export and co-development opportunities for prime contractors.
Company Profiles and Strategic Positioning of Leading Market Participants
Industry leaders occupy distinct strategic niches. BAE Systems plc and General Dynamics Corporation excel in large-scale platform integration, while L3Harris Technologies Inc. and Leonardo S.p.A. focus on advanced signal intelligence and radar warning sub-systems. Mercury Systems Inc. provides critical high-performance processing hardware, and Northrop Grumman Corporation pioneers directed energy integration.
Porter's Five Forces Analysis of Competitive Intensity
Threat of new entrants remains exceptionally low due to prohibitive capital requirements, classified security clearances, and entrenched prime contractor relationships. Bargaining power of buyers is moderate-to-high, as defense ministries dictate strict budgetary and performance metrics. Substitute threats are minimal given the irreplaceable nature of advanced naval electronic warfare.
SWOT Analysis of the Surface Electronic Warfare Improvement Program (SEWIP) Block 4 Roadmap Market
Strengths include entrenched multi-year defense contracts and high technological barriers to entry. Weaknesses involve vulnerability to federal budget sequestration and lengthy testing cycles. Opportunities lie in international allied sales and uncrewed platform integration, whereas threats encompass state-sponsored cyber espionage and component supply bottlenecks.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw material extraction (rare earth elements, specialized semiconductors) through component fabrication, sub-system integration by firms like Mercury Systems, and final platform assembly by primes such as Lockheed Martin. The chain terminates with naval end-users requiring rigorous lifecycle maintenance and software update cycles.
Investment Insights and High-Potential Areas for Capital Allocation
Investment opportunities are heavily concentrated in cyber protection systems, uncrewed deployment architectures, and directed energy countermeasures. Venture capital and corporate M&A strategies should target agile firmware developers and electromagnetic shielding innovators capable of retrofitting legacy fleet components without major dry-dock overhauls.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Surface Electronic Warfare Improvement Program (SEWIP) Block 4 Roadmap Market offers compelling growth prospects for well-positioned defense contractors. Success in this landscape requires relentless software adaptability, strict adherence to military standards, and proactive alignment with naval electrification and directed-energy mandates.
Research Methodology and Data Triangulation Protocols
Our baseline estimates are established through rigorous triangulation. We combine primary qualitative interviews with C-level defense executives and naval acquisition officials with secondary trade registry data, government defense budget filings, and macroeconomic indices. This multi-tiered approach ensures high fidelity in market sizing and forecasting.
Scope of the Report, Coverage Parameters, and Analytical Limitations
This report evaluates the global market across specified deployment modes, platforms, and technological components from 2026 to 2033. Limitations include the exclusion of classified black-budget defense allocations and unforeseen geopolitical shocks that could abruptly alter sovereign naval procurement schedules and supply chain logistics.
Recent Developments, Strategic Partnerships, and Corporate Announcements
Recent market activity is characterized by strategic teaming agreements between prime defense contractors and specialized software firms to accelerate cognitive EW testing. Noteworthy corporate announcements highlight increased R&D investments in gallium-nitride-based radar jamming systems and sea-trials for uncrewed surface vehicle electronic payload integration.